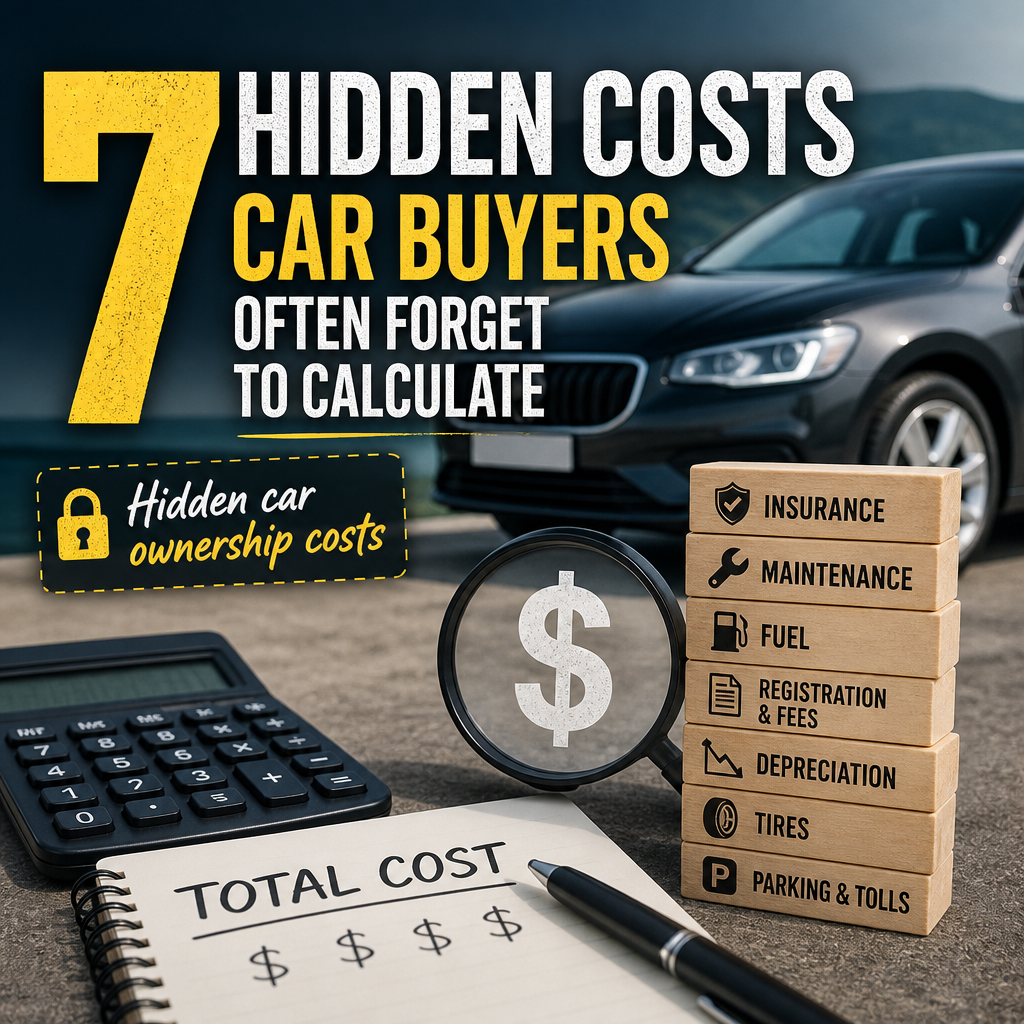
7 Hidden Costs Car Buyers Often Forget to Calculate
7 Hidden Costs Most Car Buyers Never Calculate
Buying a car is often treated as a simple equation: compare the purchase price, secure financing, and drive away. In reality, the amount printed on the window sticker is only one part of the total cost of ownership.
Many expenses appear later, sometimes gradually and sometimes in surprising bills. Understanding these hidden costs before signing a contract can help you choose a vehicle that fits your budget long after the excitement of the purchase fades.
1. Depreciation
Depreciation is the loss in a vehicle’s value over time. It is one of the largest costs of car ownership, yet buyers rarely pay it directly each month.
A new car can lose a significant portion of its value within the first few years. Luxury vehicles, electric cars, and models with frequent redesigns may depreciate especially quickly. Even if you plan to keep the vehicle for a long time, depreciation affects your trade-in value and the amount of equity you build.
Before buying, research:
- Expected resale value
- Historical depreciation for the model
- Demand for similar used vehicles
- Whether the car is due for a major redesign
A vehicle with a slightly higher purchase price may ultimately cost less if it holds its value well.
2. Insurance Premiums
Insurance costs can vary dramatically between vehicles that have similar price tags. Insurers consider factors such as repair costs, theft rates, engine performance, safety equipment, and the likelihood of expensive claims.
A sports car may carry a much higher premium than a family sedan. Likewise, a luxury vehicle can be costly to insure because replacement parts and specialized repairs are more expensive.
Get insurance quotes before purchasing, not after. Ask for estimates based on the exact trim level and features you are considering. Small differences in equipment can affect the premium.
3. Maintenance and Repairs
Every vehicle requires routine maintenance, but costs differ widely by make, model, age, and design. Oil changes, tire rotations, brake service, fluid replacements, and inspections can add up over the years.
Some vehicles also require specialized parts or technicians. European models, performance cars, and vehicles with advanced hybrid or electric systems may have higher repair bills. Even common repairs, such as replacing tires or brake components, can become expensive when premium parts are required.
Review the manufacturer’s maintenance schedule and look for long-term ownership data. A vehicle with a low monthly payment may still be expensive if its service needs are unusually high.
4. Taxes, Registration, and Dealer Fees
The advertised price usually does not include every charge due at purchase. Depending on where you live, you may need to pay sales tax, registration fees, title fees, documentation charges, and local transportation or environmental fees.
Dealer add-ons can also increase the final price. These may include:
- Window etching
- Paint protection
- Fabric protection
- Extended warranties
- Preinstalled accessories
- Administrative or preparation fees
Request an itemized “out-the-door” price before agreeing to buy. This figure gives you a more realistic view of the total upfront cost and makes it easier to compare dealerships.
5. Fuel or Charging Costs
Fuel economy is easy to overlook when comparing monthly payments, but it can have a major impact on your budget. A vehicle that uses several more gallons each week may cost hundreds or thousands of dollars more annually than an efficient alternative.
Electric vehicles have charging costs rather than fuel expenses, but those costs are not always straightforward. Home charging may require equipment installation, electrical upgrades, or changes to your utility plan. Public charging can also be more expensive, especially at fast-charging stations.
Estimate your annual mileage and calculate expected energy costs using realistic local fuel or electricity prices.
6. Financing Expenses
The monthly payment does not reveal the full cost of an auto loan. Interest, loan length, fees, and the amount of your down payment all influence what you ultimately pay.
A longer loan term may make payments more manageable, but it can lead to substantially more interest. It can also leave you owing more than the car is worth for much of the loan period.
Compare lenders before visiting the dealership, and focus on the annual percentage rate rather than only the payment amount. Be cautious about rolling negative equity, warranties, or other products into the loan, since doing so increases both the balance and the interest charged.
7. Parking, Accessories, and Convenience Costs
The vehicle itself may require additional spending to fit your lifestyle. Urban drivers may face monthly parking fees, garage costs, tolls, or residential permits. Families may need roof racks, cargo organizers, child-seat accessories, or all-weather mats.
Some vehicles also require seasonal equipment, such as winter tires and storage. Owners of larger trucks or SUVs may spend more on parking, tolls, and replacement tires simply because of the vehicle’s size.
Make a list of the extras you are likely to need during the first year. These costs may not appear in the sales contract, but they are still part of the real ownership budget.
Calculate the Full Cost Before You Buy
The smartest way to evaluate a vehicle is to look beyond its purchase price. Add financing, insurance, fuel, maintenance, depreciation, taxes, and lifestyle-related expenses to estimate the total cost of ownership.
A car that seems affordable in the showroom may be expensive over five years. Conversely, a slightly more expensive model could save money through better fuel economy, lower insurance rates, and stronger resale value. Calculating these hidden costs in advance can help you make a decision based on the vehicle’s true financial impact—not just its monthly payment.